
Weekly round up & the week ahead

Paul Reilly
Chief Commercial Officer
Weekly Currency Update
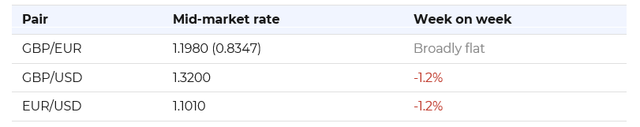
Indicative mid-market rates, Monday 16 November, morning
Week in review - a “jumbo” Fed hike is on the table
US inflation data and a hawkish Fed voice have put a “jumbo” December hike on the table. October CPI rose 0.4% on the month against 0.3% expected, with core up 0.3% against 0.2%. Ahead of the release, Fed Governor Waller said a 50bp hike should be considered in December if core came in at 0.3% or above. Markets now fully price a 25bp increase at the 9 December meeting, and the risk of a larger move has grown. The dollar firmed, with GBP/USD and EUR/USD both down around 1.2% on the week, to 1.3200 and 1.1010 this morning. There is a caveat: the figures cover a period when oil spiked towards $120. Brent has since fallen around 18% from its 30 October peak to roughly $96, which should ease headline inflation in November and December. For now, though, the Fed’s concern is core inflation, and that is keeping the dollar supported.
UK rate expectations firmed too, but by less. Bank of England Deputy Governor Clare Lombardelli declined to rule out back-to-back hikes following November’s first increase, and markets now price better than an 80% chance of another 25bp rise in December. ECB expectations edged up as well, though only marginally. GBP/EUR was little changed at around 1.198, as both currencies lost ground to the dollar.
Week ahead - UK inflation and the Fed minutes take centre stage
UK data is the focus. Tuesday’s labour market figures are expected to show unemployment steady at 4.7% and earnings growth cooling slightly to 3.6%. Wednesday’s October CPI is the main event: forecasts point to headline inflation edging up to 3.7% from 3.5%, with core steady at 2.8%. A firmer print would reinforce December hike pricing and support sterling, while a softer one would raise doubts. Retail sales follow on Friday, with a small fall in core sales expected, alongside the EU-UK summit.
In the US, the Fed minutes and a long list of speakers will be watched closely. October retail sales and industrial production land on Tuesday, with headline sales expected flat and the control group, a key core measure, up 0.4%. On Wednesday evening the minutes of the 27-28 October meeting are published, and the Fed speakers will test how widely Waller’s views are shared.
For the euro, the data remains soft. Industrial production for September is due on Monday, after output fell in each of the three months to August. Final October inflation figures arrive on Wednesday, and ECB President Lagarde speaks on Wednesday, Thursday and Friday.
Volatility is the opportunity. With UK inflation, the Fed minutes and a possible 50bp hike all in play, now is a good time to review your euro and dollar exposures. Talk to your Clear Treasury dealer about protecting your rate, and ask for our latest analysis and forecasts. Give us a call, email us, or request a call-back.